author avatar
Mark Chandik

May 8, 2023

Crosscurrents

Weekly Market Commentary

Here’s a paradox. What happens when an immovable object runs into an irresistible force? In today’s investing world, the Federal Reserve has been that immovable object, jacking up interest rates in order to quell inflation.

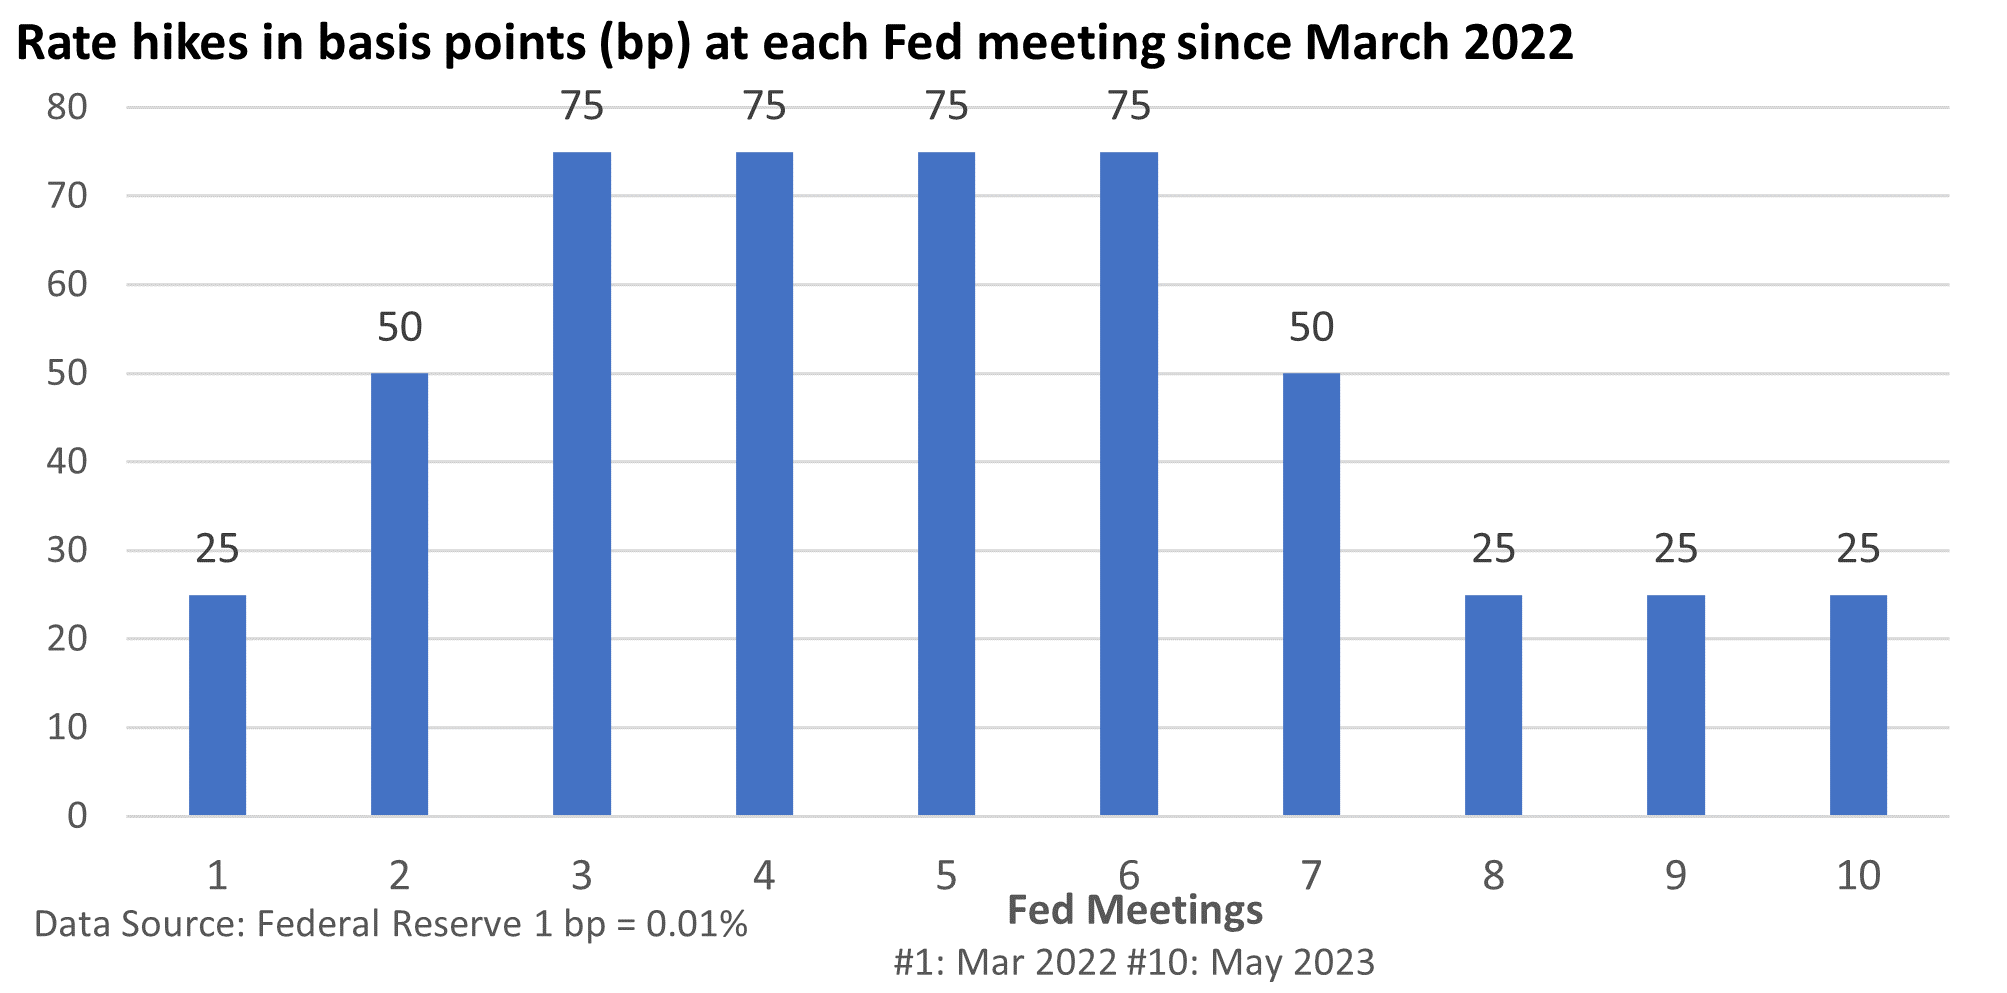
Today’s rate-hike cycle is the fastest since 1980. The Fed has raised the fed funds rate by 500 basis points (bp, 1 bp = 0.01%), or 5 percentage points, since March 2022.
But the Fed’s war on inflation appears to be on a collision course with a banking crisis that flared up again last week. It’s creating a new headache for the Fed. Raising rates conflicts with the goal of easing pressure on banks. It has forced a more cautious outlook from the Fed.

What happened? With a helping hand from the FDIC, the deposits and most assets of First Republic Bank (FRB) were purchased last week by JPMorgan Chase (JPM). End of crisis? Not so fast. The market went after another next regional bank.

It’s not based on the economic fundamentals. Instead, it’s psychology and fear in play.

“The tension between poor market sentiment and strong liquidity at regional banks is difficult to reconcile as investors take a draconian view of banks’ capital and operating models,” Bloomberg Intelligence analyst Herman Chan said. Others are less sure.

What happened Wednesday? The Fed hiked its key lending rate, the fed funds rate, by 25 bp to 5.00 – 5.25%. Rhetorically, it kept up its tough talk on inflation. It left the door open to another rate increase in June. Unlike prior hikes, the tone was much less definitive.

Investors are currently trying to price in about three 25 bp rate cuts this year, according to the CME FedWatch tool. But Fed Chief Powell pushed back.

We “have a view that inflation is going to come down, but it’ll take some time. And in that world, if that forecast is broadly right, it would not be appropriate to cut rates, and we won’t cut rates,” he said at his press conference.

That sparked Wednesday’s selloff, which continued into Thursday. It’s one more reason a well-diversified portfolio tailored to your long-term goals helps manage short-term volatility.

For now, the Fed is betting it can keep its attention on inflation while using other tools to support banks that are in need.

author avatar
Mark Chandik

Reproduction Prohibited without Express Permission. Copyright FDP Wealth Management. All rights reserved. Advisory Services offered through FDP Wealth Management, LLC, a state Registered Investment Adviser and Valmark Advisers, Inc. a SEC Registered Investment Advisor. Securities offered through ValMark Securities, Inc., Member FINRA/SIPC. 130 Springside Drive, Suite 300, Akron, OH 44333-2431 800.765.5201 Prosperity Partners and FDP Wealth Management, LLC are separate entities from ValMark Securities, Inc. and Valmark Advisers, Inc. Prosperity Partners, FDP Wealth Management, LLC, ValMark Securities, Inc., Valmark Advisers Inc., and their representatives do not offer tax advice. You should consult your tax professional regarding your individual circumstances. Indices are unmanaged and cannot be invested directly in. Past performance is not a guarantee of future results.

Indices are unmanaged and do not incur fees, one cannot directly invest in an index. You should consult your tax professional regarding your individual circumstances. This information is provided by Financial Jumble, LLC. Financial Jumble, LLC is a separate entity from ValMark Securities, Inc. and ValMark Advisers, Inc.

RELATED POSTS

A Hotter August CPI Builds Rate Hike Momentum

First, let’s clarify that any attempt to predict the Federal Reserve’s actions this week is, at best, an educated guess. Fed Chair Kevin Warsh has struck a hawkish tone, and the odds of a quarter-point increase in the fed funds rate are 87%, according to the CME Group. It was 59% on September 4.

Behind the Jobs Report

On Friday, the US Bureau of Labor Statistics (BLS) reported that nonfarm payrolls rose by a much greater-than-expected 162,000 jobs in August. The unemployment rate held steady at 4.1%.

Location Location Location

The graphic below compares the change in home prices, adjusted for inflation, for various US cities. For example, the average USA home price has topped inflation by 238% since 1948. Why has there been such a wide trajectory in prices, and why have they proven so persistent?

Rising Yields Faily to Derail Stocks

This year, the stock market has risen significantly. Lingering worries about oil prices, inflation, the war with Iran, and the possibility of an AI bubble haven’t subsided. But the economy is expanding, corporate profits have been strong, and the S&P 500 Index set a new high last week, according to the Wall Street Journal.

All Gas, No Brakes: Profits Soar in Q2

In a solid earnings season, we’d generally expect S&P 500 companies to deliver double-digit profit growth, meaning earnings growth of at least 10% versus a year ago (20% tops). That’s not a hard-and-fast rule, but it provides a useful benchmark for evaluating the strength of a quarter.