author avatar
Mark Chandik

Feb 21, 2023

The Long and Winding Road to Lower Inflation

Weekly Market Commentary

The Fed’s road to 2% annual inflation took a curious turn last week, disappointing some investors that had been expecting continued progress on inflation.

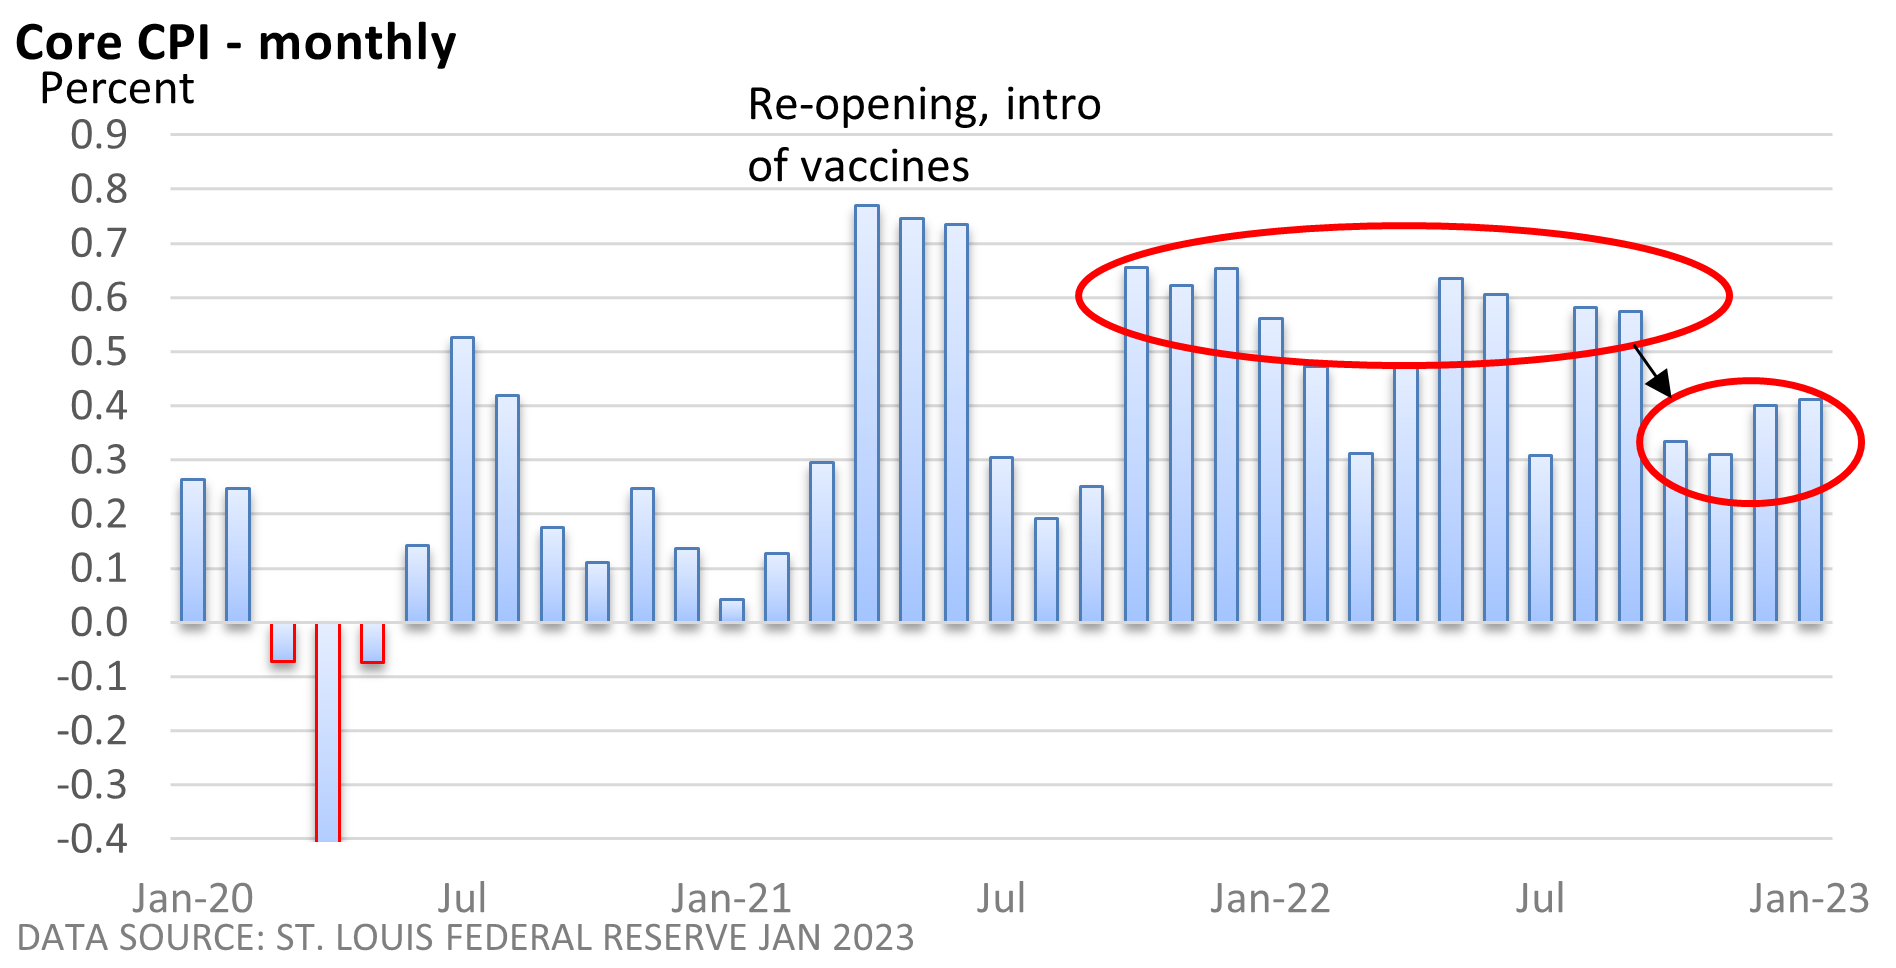
The U.S. Bureau of Labor Statistics reported that the January Consumer Price Index rose 0.5% in January, while the core rate, which excludes food and energy, rose 0.4%.

The numbers are down from last year’s peak, but they have edged above the recent low. The core rate of inflation is up over the last two months, averaging about 0.4% per month. It’s well above the Fed’s annual target of 2%.
Services continue to rise at a fast pace, but consumer goods, which had been a bright spot, unexpectedly rose.

Fed Chief Jerome Powell said earlier in the month that it is too soon to declare victory on inflation, but he touted progress, pointing to the disinflationary trend in consumer goods. In fact, he used the term disinflation 11 times at his February 1 press conference.

Let’s not confuse disinflation with deflation. Disinflation simply means that the rate of inflation is slowing. Deflation is defined as an actual decline in prices.

If Powell had last week’s data then, his cautiously optimistic tone may have been more subdued.
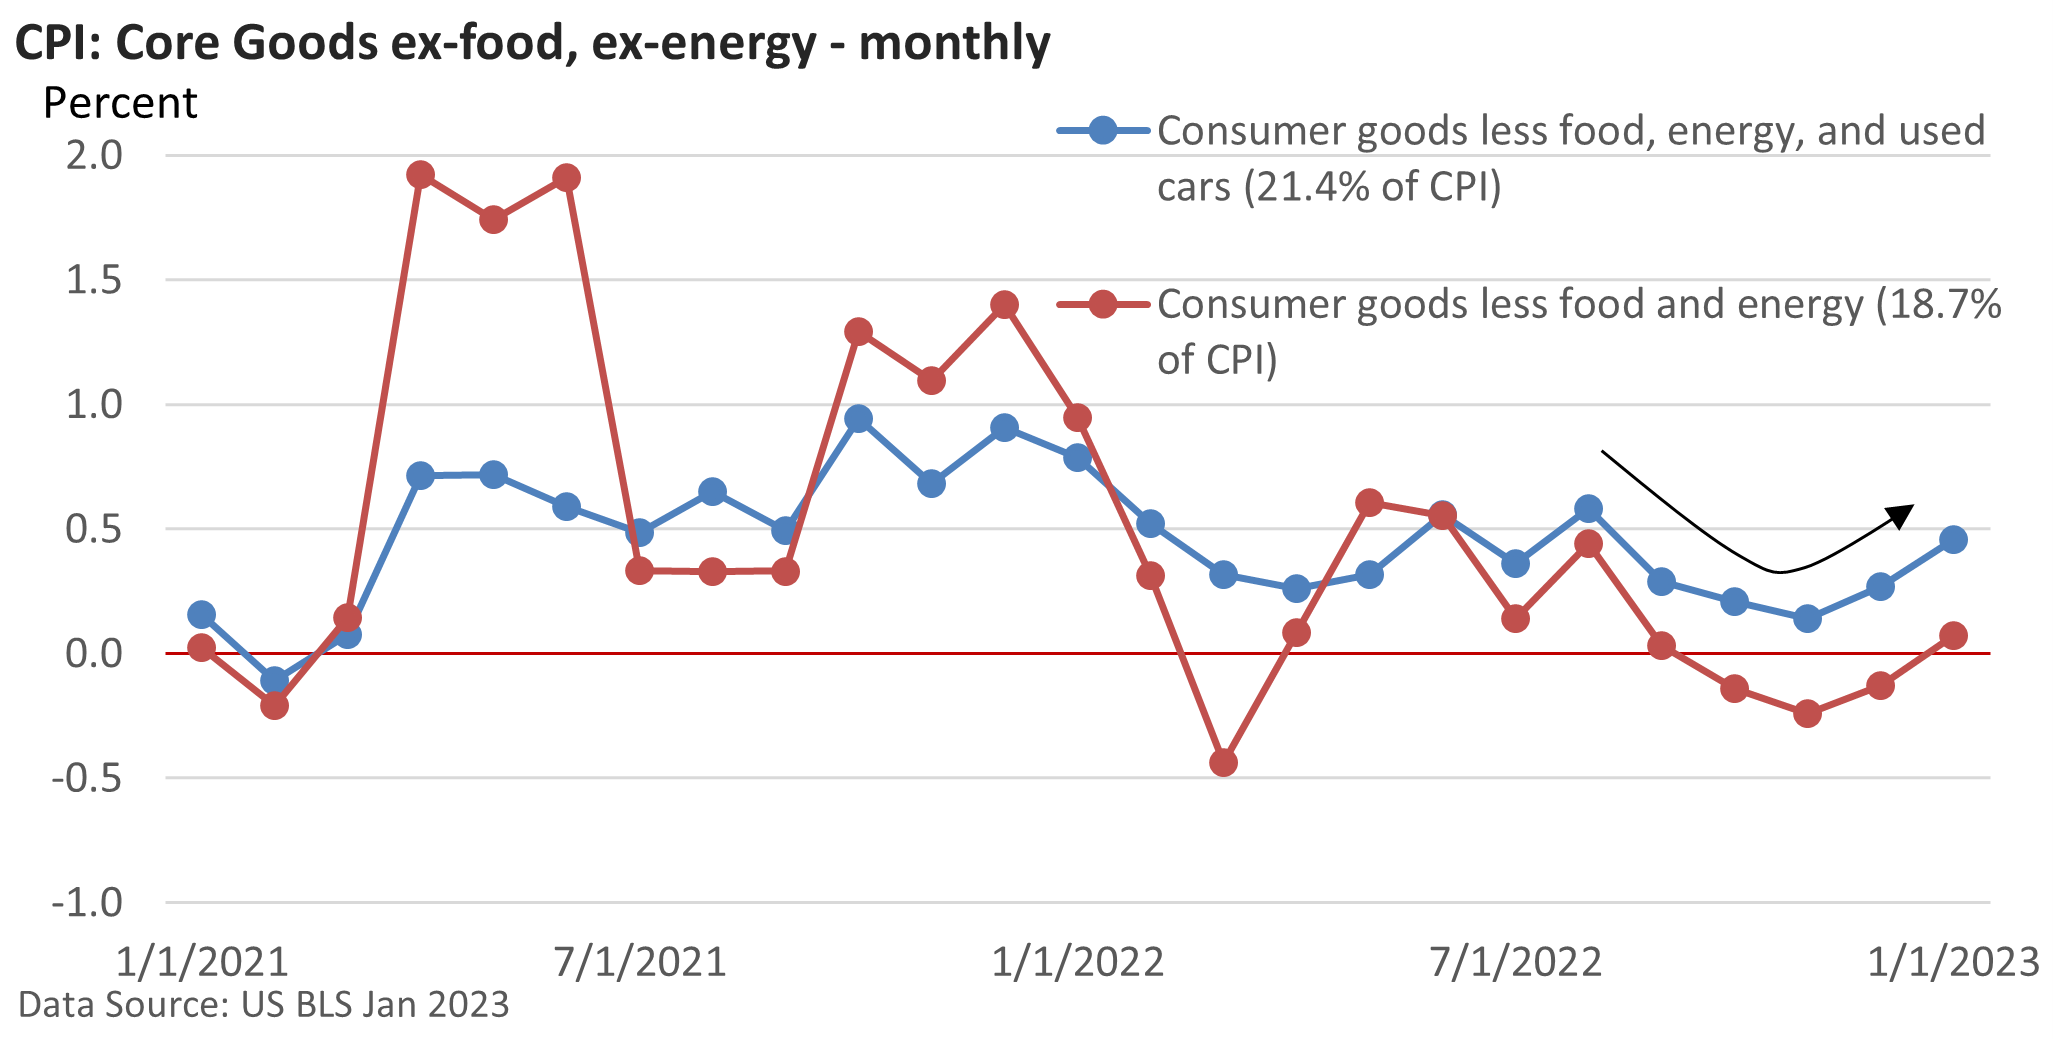
Perhaps what we are seeing is lumpy data—weakness in November and December followed by strength in January. In other words, the long-term upward trend in the economy is intact, but month-to-month activity is uneven.

It’s also a new year and some firms may have taken advantage of the calendar to raise prices.

But given the inflation data last week, January’s blockbuster payroll number, and the upturn in consumer spending last month, investor expectations of a near-term peak in rates have receded.

author avatar
Mark Chandik

Reproduction Prohibited without Express Permission. Copyright FDP Wealth Management. All rights reserved. Advisory Services offered through FDP Wealth Management, LLC, a state Registered Investment Adviser and Valmark Advisers, Inc. a SEC Registered Investment Advisor. Securities offered through ValMark Securities, Inc., Member FINRA/SIPC. 130 Springside Drive, Suite 300, Akron, OH 44333-2431 800.765.5201 Prosperity Partners and FDP Wealth Management, LLC are separate entities from ValMark Securities, Inc. and Valmark Advisers, Inc. Prosperity Partners, FDP Wealth Management, LLC, ValMark Securities, Inc., Valmark Advisers Inc., and their representatives do not offer tax advice. You should consult your tax professional regarding your individual circumstances. Indices are unmanaged and cannot be invested directly in. Past performance is not a guarantee of future results.

Indices are unmanaged and do not incur fees, one cannot directly invest in an index. You should consult your tax professional regarding your individual circumstances. This information is provided by Financial Jumble, LLC. Financial Jumble, LLC is a separate entity from ValMark Securities, Inc. and ValMark Advisers, Inc.

RELATED POSTS

A Hotter August CPI Builds Rate Hike Momentum

First, let’s clarify that any attempt to predict the Federal Reserve’s actions this week is, at best, an educated guess. Fed Chair Kevin Warsh has struck a hawkish tone, and the odds of a quarter-point increase in the fed funds rate are 87%, according to the CME Group. It was 59% on September 4.

Behind the Jobs Report

On Friday, the US Bureau of Labor Statistics (BLS) reported that nonfarm payrolls rose by a much greater-than-expected 162,000 jobs in August. The unemployment rate held steady at 4.1%.

Location Location Location

The graphic below compares the change in home prices, adjusted for inflation, for various US cities. For example, the average USA home price has topped inflation by 238% since 1948. Why has there been such a wide trajectory in prices, and why have they proven so persistent?

Rising Yields Faily to Derail Stocks

This year, the stock market has risen significantly. Lingering worries about oil prices, inflation, the war with Iran, and the possibility of an AI bubble haven’t subsided. But the economy is expanding, corporate profits have been strong, and the S&P 500 Index set a new high last week, according to the Wall Street Journal.

All Gas, No Brakes: Profits Soar in Q2

In a solid earnings season, we’d generally expect S&P 500 companies to deliver double-digit profit growth, meaning earnings growth of at least 10% versus a year ago (20% tops). That’s not a hard-and-fast rule, but it provides a useful benchmark for evaluating the strength of a quarter.