author avatar
Mark Chandik

Dec 5, 2022

Too Much Hiring

Weekly Market Commentary

Can there be too much hiring? Can job growth be too fast? It seems like an odd question. But following a better-than-expected jobs report on Friday and the initial negative reaction (shares pared losses and finished mixed), the question is worth exploring.

The U.S. Bureau of Labor Statistics reported nonfarm payrolls rose 263,000 in November, beating the CNBC consensus estimate of 200,000. The unemployment rate remained at 3.7%.
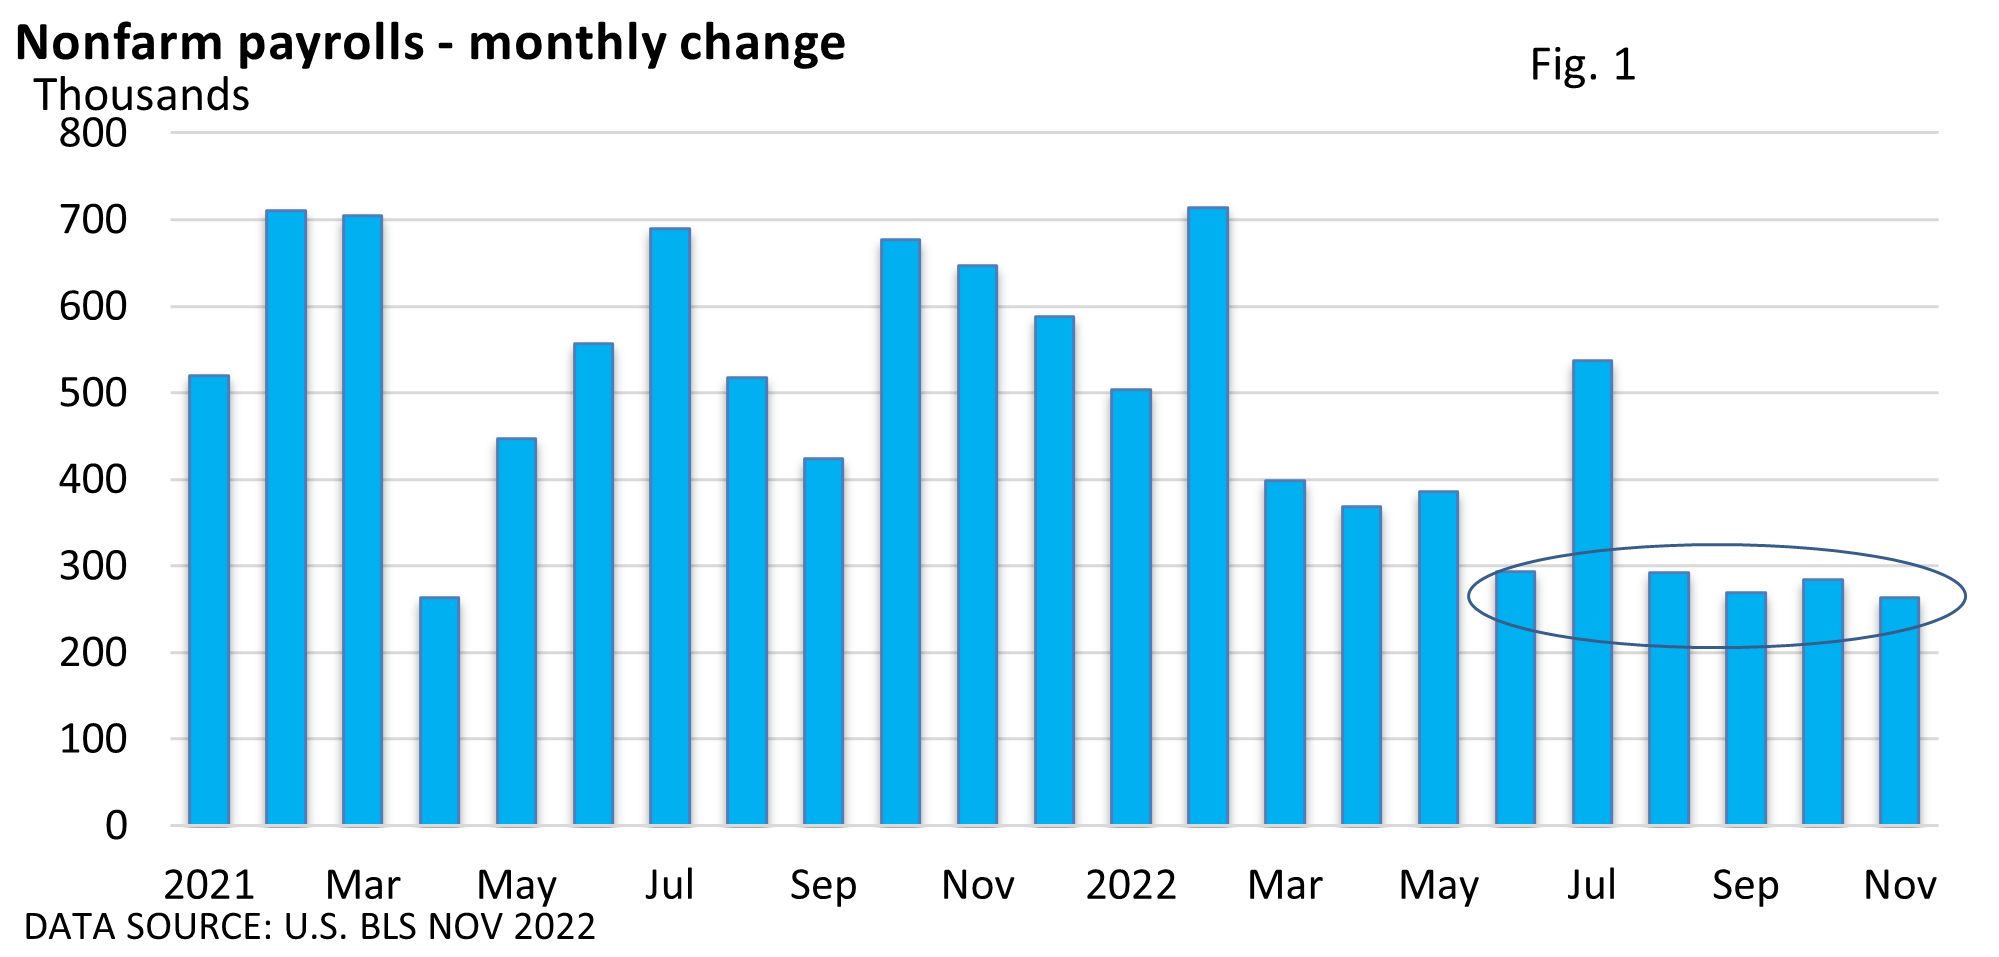
The trend in Figure 1 illustrates a moderation in job growth, but nothing concerning.

Five of the last six months have held in a narrow but historically solid range of 263,000 to 293,000. Investors initially reacted negatively to the report, and it seems fair to inquire why analysts had expected a big slowdown in November. Layoffs aren’t up, and job openings remain high.

So, why the sour mood? Sometimes the interest of Wall Street (investors) lines up with those of Main Street, but not always.

Main Street is benefiting from the labor shortage and upbeat job growth, as both are helping to support wages.

But Wall Street contends that robust hiring and fast wage gains add to inflation. You see, interest rates have skyrocketed this year in response to high inflation.

Wage growth that is too fast usually forces businesses to raise prices since labor costs are among the biggest expenses for most firms.

And, if inflation remains sticky, we’re likely to see rates continue to rise and remain at a higher level for a longer period. That creates added headwinds for stocks.

There will come a time when job growth slows. Several economic indicators suggest that a recession may be unavoidable next year. Historically, economic weakness sends the jobless rate higher and slows wage hikes.

The Fed’s goal, however, is to gently slow the economy and bring down the rate of inflation. It’s a very narrow path and may not be achievable. Next year, we may be having a different conversation, but today’s prevailing themes continue to be interest rates and inflation.

author avatar
Mark Chandik

Reproduction Prohibited without Express Permission. Copyright FDP Wealth Management. All rights reserved. Advisory Services offered through FDP Wealth Management, LLC, a state Registered Investment Adviser and Valmark Advisers, Inc. a SEC Registered Investment Advisor. Securities offered through ValMark Securities, Inc., Member FINRA/SIPC. 130 Springside Drive, Suite 300, Akron, OH 44333-2431 800.765.5201 Prosperity Partners and FDP Wealth Management, LLC are separate entities from ValMark Securities, Inc. and Valmark Advisers, Inc. Prosperity Partners, FDP Wealth Management, LLC, ValMark Securities, Inc., Valmark Advisers Inc., and their representatives do not offer tax advice. You should consult your tax professional regarding your individual circumstances. Indices are unmanaged and cannot be invested directly in. Past performance is not a guarantee of future results.

Indices are unmanaged and do not incur fees, one cannot directly invest in an index. You should consult your tax professional regarding your individual circumstances. This information is provided by Financial Jumble, LLC. Financial Jumble, LLC is a separate entity from ValMark Securities, Inc. and ValMark Advisers, Inc.

RELATED POSTS

Rising Mortgage Rates: A Consequence of Higher Treasury Yields

Mortgage rates have moved sharply higher in recent months, creating a noticeable headwind for homebuyers and homeowners looking to refinance.

When Bad News Is Good News

Released by the US Bureau of Labor Statistics (BLS), September’s nonfarm payroll report came in lighter than expected, and the unemployment rate unexpectedly inched higher.

Rising Bond Yields and the Stock Market

“Bond Selloff Deepens After 30-Year Yield Hits Highest Level Since 2004,” declared Bloomberg News last week. CNBC echoed the sentiment with “10-Year Treasury Yield Rockets to 19-Year High.”

The Fed Hikes Rates: What Investors Should Know

In his opening remarks in a speech last month at the Federal Reserve Bank of Kansas City’s Economic Symposium, Fed Chief Kevin Warsh said, “(Event) planners have some recreation options lined up for later today.

A Hotter August CPI Builds Rate Hike Momentum

First, let’s clarify that any attempt to predict the Federal Reserve’s actions this week is, at best, an educated guess. Fed Chair Kevin Warsh has struck a hawkish tone, and the odds of a quarter-point increase in the fed funds rate are 87%, according to the CME Group. It was 59% on September 4.