author avatar
Mark Chandik

Jul 20, 2026

Chips in Flux

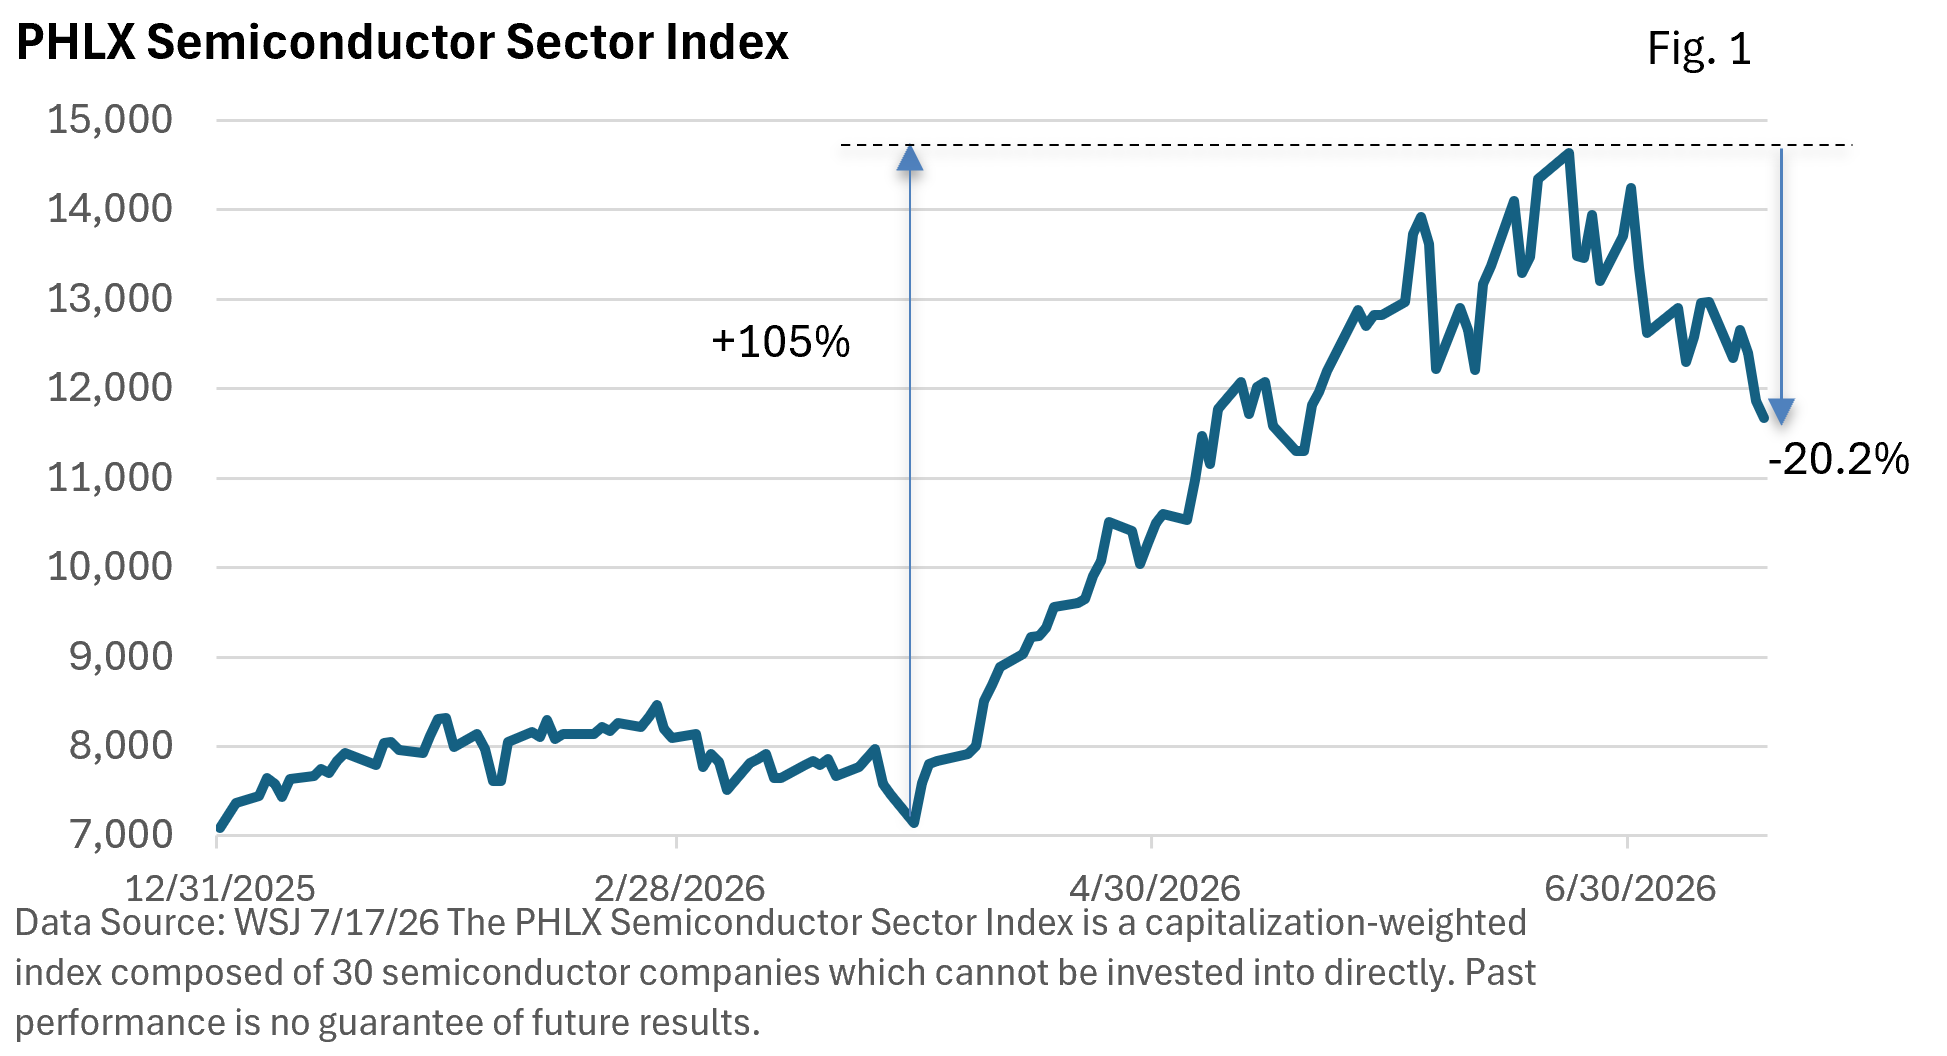
Since the most recent market low at the end of March, semiconductors (microchips, commonly called chip stocks) have been a very popular trade. In less than three months, the PHLX Semiconductor Index has more than doubled—see Figure 1.
Line chart of the PHLX Semiconductor Sector Index from Dec 2025 to Jun 2026, showing a +105% rise to a peak and a -20% drop by June 2026 (data note included).
Investors are expecting a staggering rise in second-quarter earnings for the semiconductor sector, with profits expected to rise by 131%, according to MarketWatch.

But why have chip stocks entered a bear market—a drop of at least 20% from peak to trough? The index is down 20.2% from its June 22 peak. It remains substantially higher than the late-March low and the end of last year.

For starters, chips became a crowded trade, i.e., a large number of investors holding the same position. With investors heavily concentrated on the same side of the market, liquidity risks build beneath the surface, creating the potential for a rapid and disorderly unwind if the trade begins to reverse.

Figure 2 illustrates the high level of volatility since late April, both to the upside and downside.
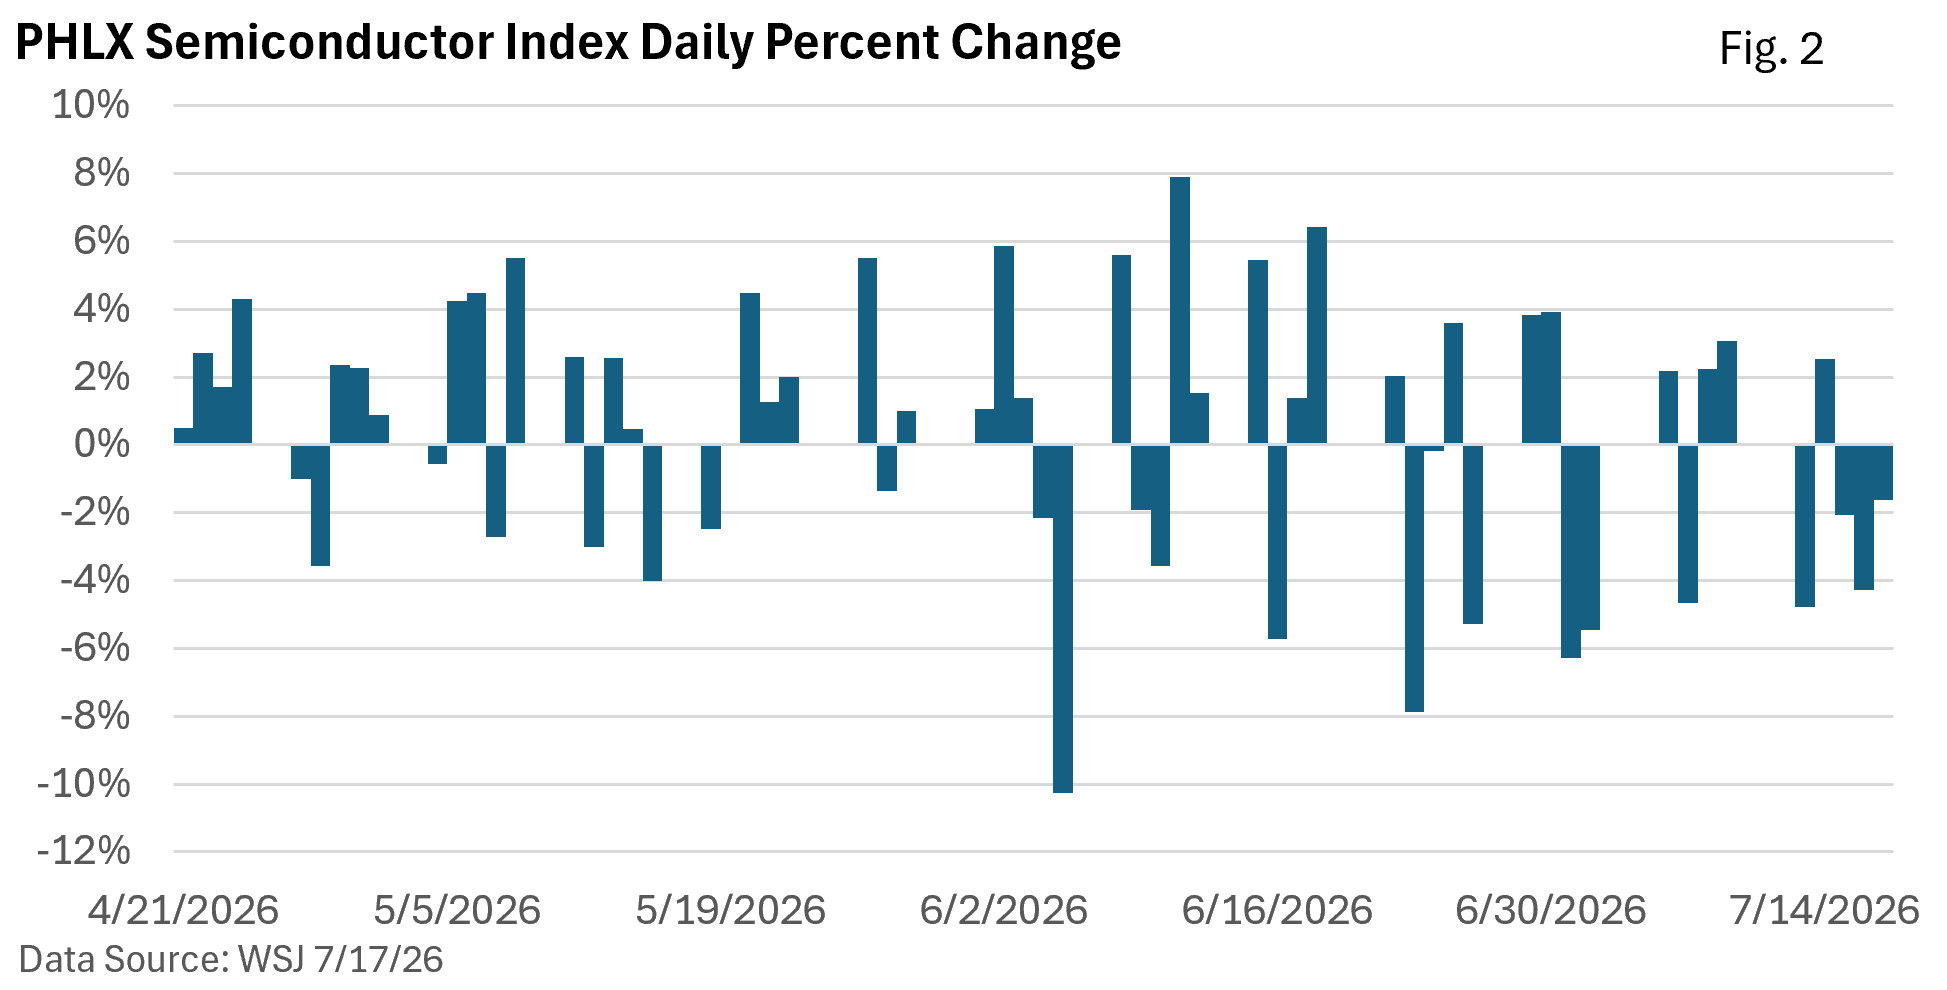
Bar chart of PHLX Semiconductor Index daily percent changes (Apr 21–Jul 14, 2026), with daily gains and losses from about -10% to +9%.
What’s going on in recent months? Semiconductor stocks took off as massive demand from the buildout of AI data centers fueled huge purchases of memory chips. Infrastructure needs are enormous, including demand for memory chips from these chip makers.

But investors are constantly reassessing how sustainable the AI boom really is. Besides, the production cycle for chip makers has historically been feast-or-famine.

In addition, have valuations in this sector already risen to a level that prices in stellar growth? Of course, that’s a difficult question to answer, but it may be playing a role in recent volatility.

LPL Research recently opined, “The most dangerous investment mistakes often begin with an inability to imagine outcomes that differ from what the market expects.

LPL added, “That does not mean investors should reflexively bet against strong trends, because momentum is real and great businesses can stay great for a long time, but when an investment thesis depends on outcomes that are inherently unknowable, imagination becomes a risk-management tool.”

How strong has demand been? “The computing power of the total stock of AI chips has grown at 3.4 times per year, doubling every 7 months since 2022, based on revenue data, other financial disclosures, and analyst reports,” according to Epoch AI.

The recent pullback in semiconductor stocks may simply represent a healthy correction, helping to flush out excess optimism and speculative froth.

For now, AI remains in a powerful cycle as hyperscalers try to catch up and anticipate future demand for AI.

author avatar
Mark Chandik

Reproduction Prohibited without Express Permission. Copyright FDP Wealth Management. All rights reserved. Advisory Services offered through FDP Wealth Management, LLC, a state Registered Investment Adviser and Valmark Advisers, Inc. a SEC Registered Investment Advisor. Securities offered through ValMark Securities, Inc., Member FINRA/SIPC. 130 Springside Drive, Suite 300, Akron, OH 44333-2431 800.765.5201 Prosperity Partners and FDP Wealth Management, LLC are separate entities from ValMark Securities, Inc. and Valmark Advisers, Inc. Prosperity Partners, FDP Wealth Management, LLC, ValMark Securities, Inc., Valmark Advisers Inc., and their representatives do not offer tax advice. You should consult your tax professional regarding your individual circumstances. Indices are unmanaged and cannot be invested directly in. Past performance is not a guarantee of future results.

Indices are unmanaged and do not incur fees, one cannot directly invest in an index. You should consult your tax professional regarding your individual circumstances. This information is provided by Financial Jumble, LLC. Financial Jumble, LLC is a separate entity from ValMark Securities, Inc. and ValMark Advisers, Inc.

RELATED POSTS

A Hotter August CPI Builds Rate Hike Momentum

First, let’s clarify that any attempt to predict the Federal Reserve’s actions this week is, at best, an educated guess. Fed Chair Kevin Warsh has struck a hawkish tone, and the odds of a quarter-point increase in the fed funds rate are 87%, according to the CME Group. It was 59% on September 4.

Behind the Jobs Report

On Friday, the US Bureau of Labor Statistics (BLS) reported that nonfarm payrolls rose by a much greater-than-expected 162,000 jobs in August. The unemployment rate held steady at 4.1%.

Location Location Location

The graphic below compares the change in home prices, adjusted for inflation, for various US cities. For example, the average USA home price has topped inflation by 238% since 1948. Why has there been such a wide trajectory in prices, and why have they proven so persistent?

Rising Yields Faily to Derail Stocks

This year, the stock market has risen significantly. Lingering worries about oil prices, inflation, the war with Iran, and the possibility of an AI bubble haven’t subsided. But the economy is expanding, corporate profits have been strong, and the S&P 500 Index set a new high last week, according to the Wall Street Journal.

All Gas, No Brakes: Profits Soar in Q2

In a solid earnings season, we’d generally expect S&P 500 companies to deliver double-digit profit growth, meaning earnings growth of at least 10% versus a year ago (20% tops). That’s not a hard-and-fast rule, but it provides a useful benchmark for evaluating the strength of a quarter.