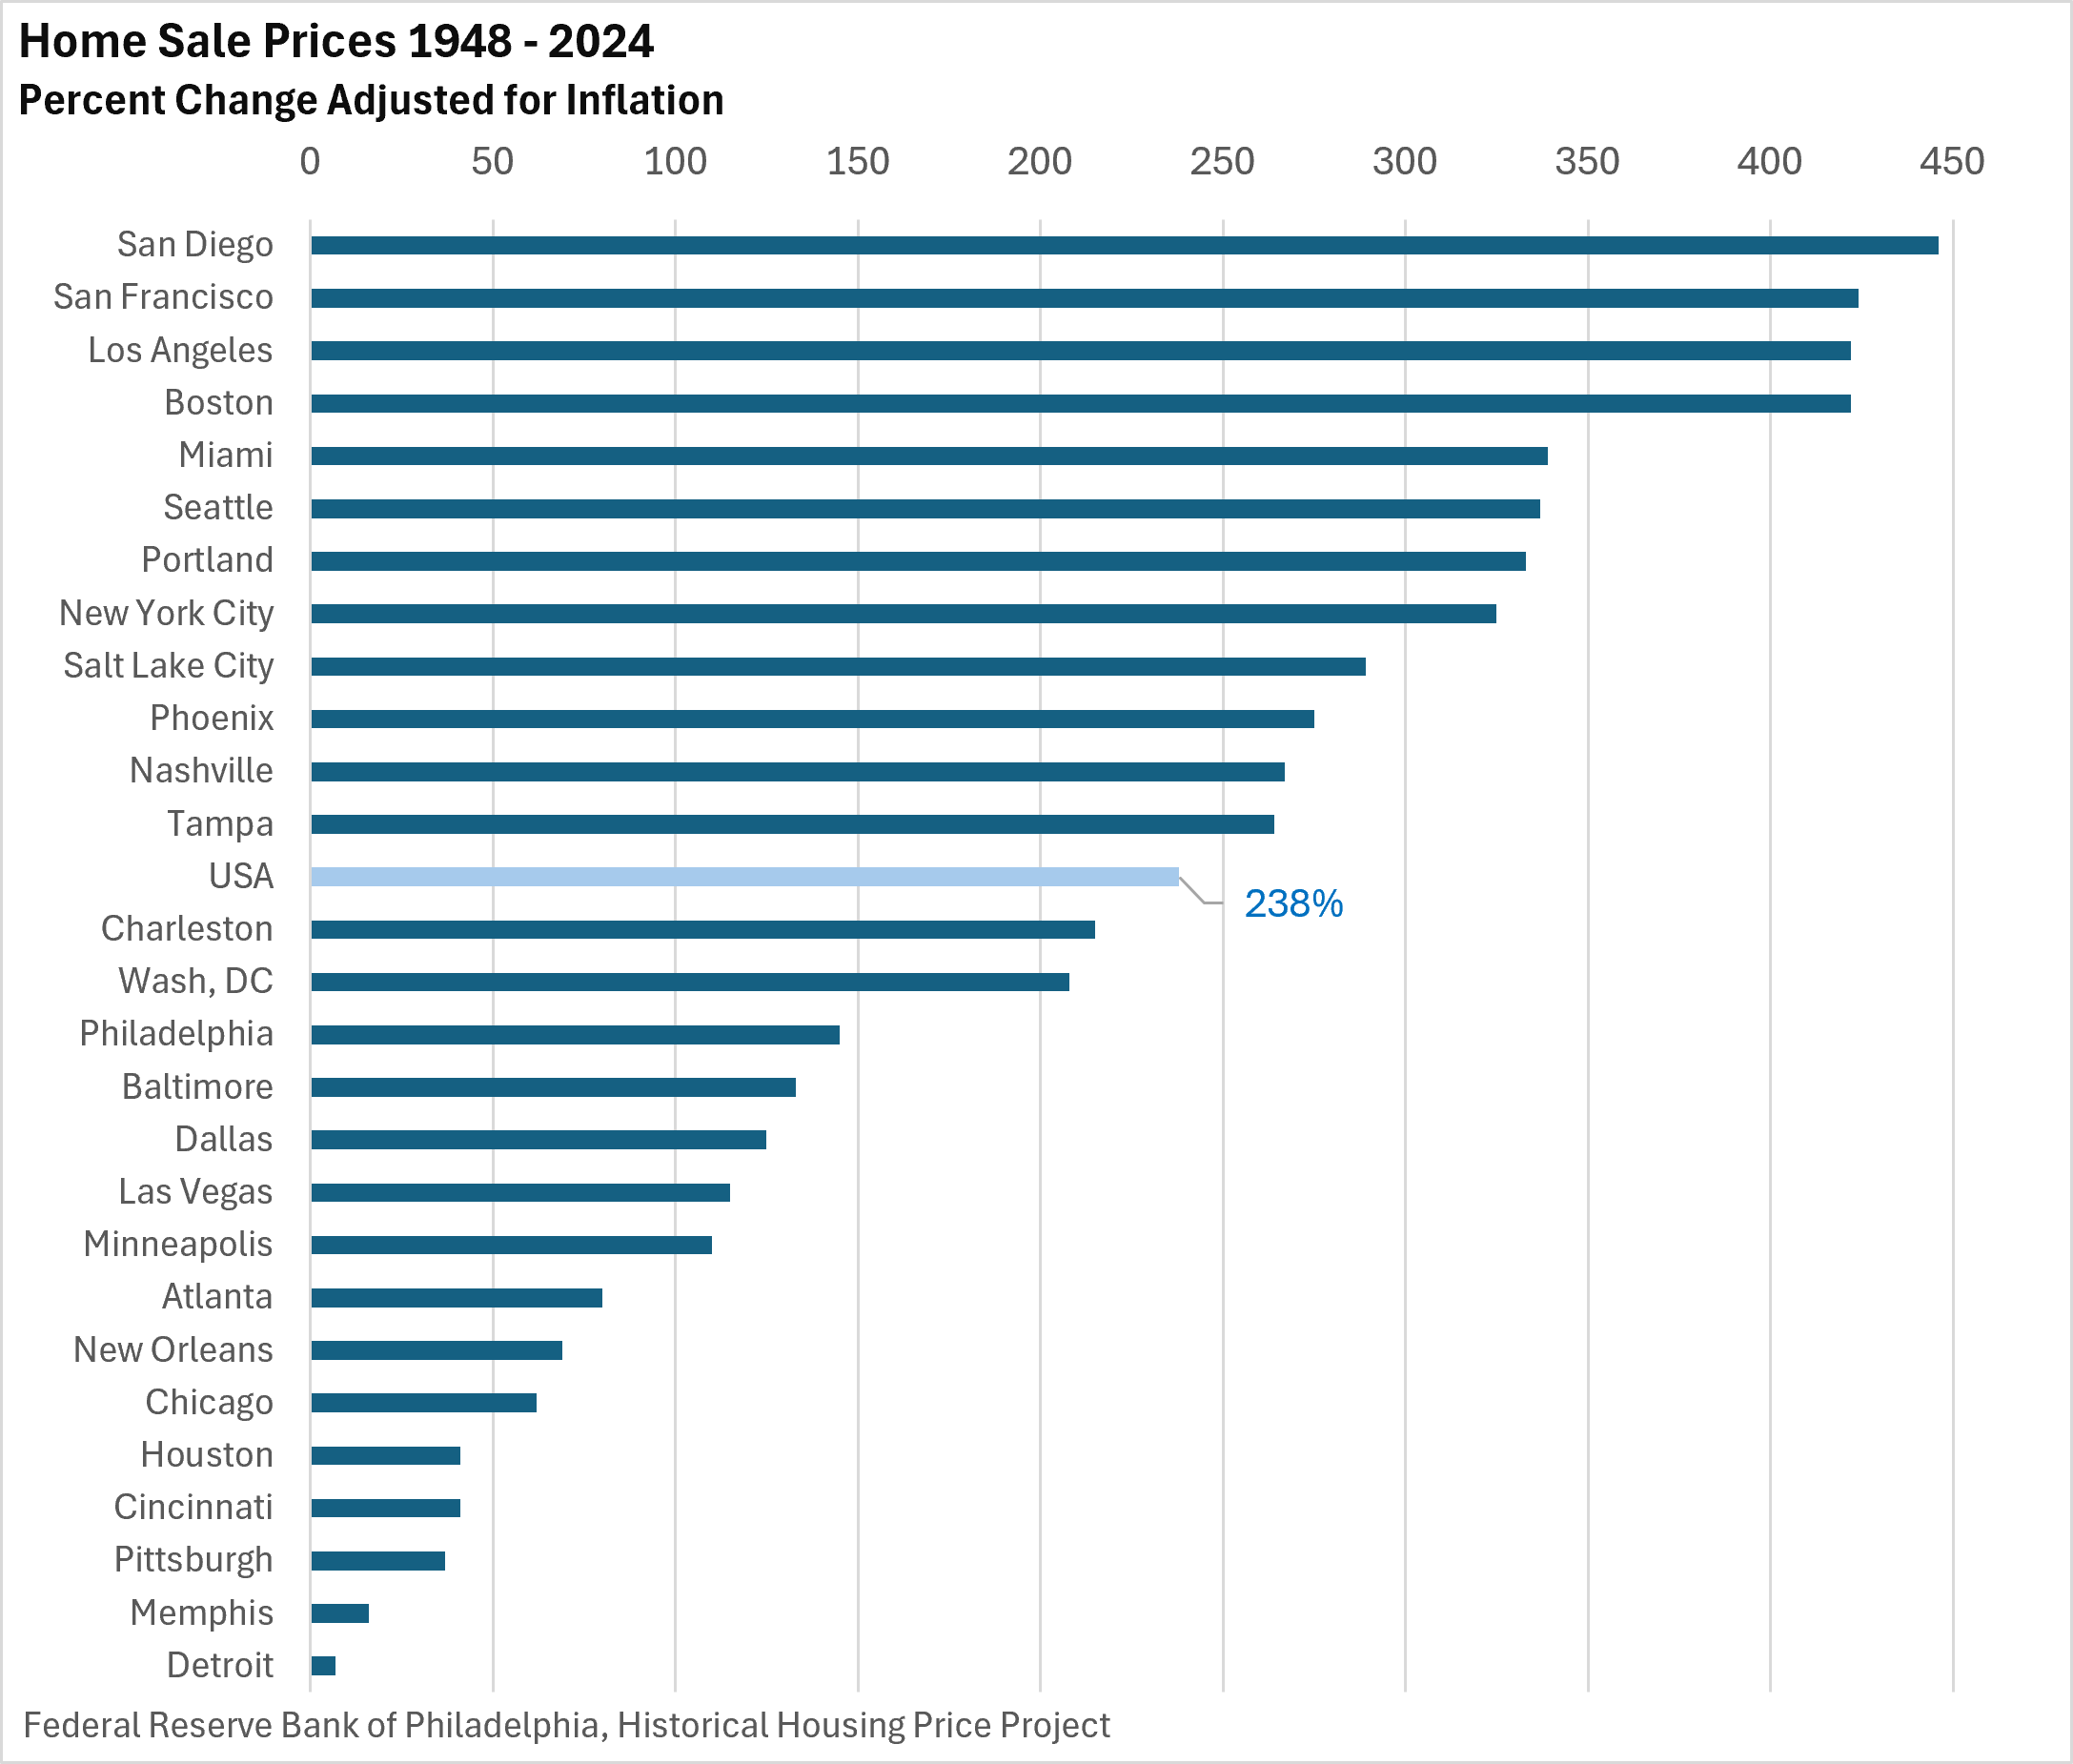
The graphic below compares the change in home prices, adjusted for inflation, for various US cities. For example, the average USA home price has topped inflation by 238% since 1948.
Note that yields briefly snuck under 4% just before the war started. In part, blame rising oil prices and fears that higher oil and other commodities might boost overall inflation at home.
For bondholders, rising yields translate into lower prices, since yields and prices move in opposite directions.
For those looking to buy a home and lock in a mortgage rate, the 30-year mortgage tracks the 10-year yield closely.
Just before the war began, Freddie Mac’s weekly survey recorded an average rate of 5.98%. As of last Thursday, the 30-year mortgage averaged 6.67%, according to the survey.
Yet, despite higher long-term Treasury yields, stocks have had a good run this year, though the market has experienced bouts of volatility, which is normal.
You see, rising bond yields would be expected to create stiffer headwinds for equities.
If an investor can earn a higher return from a Treasury bond, they may choose Treasuries over stocks, as attractive yields could encourage some to reallocate funds within their portfolios.
Higher yields could also slow economic growth, which in turn would likely slow corporate profits.
But the stock market has defied the rise in yields, as booming corporate profits have provided a strong tailwind.
From another perspective, rising bond yields have yet to put downward pressure on stocks and may have simply slowed the market’s rise.
