author avatar
Mark Chandik

May 5, 2025

Front-Running Tariffs Distort GDP

The U.S. Bureau of Economic Analysis (BEA) reported that first quarter Gross Domestic Product (GDP), which is the broadest measure of economic activity, fell at an annualized pace of 0.3%.
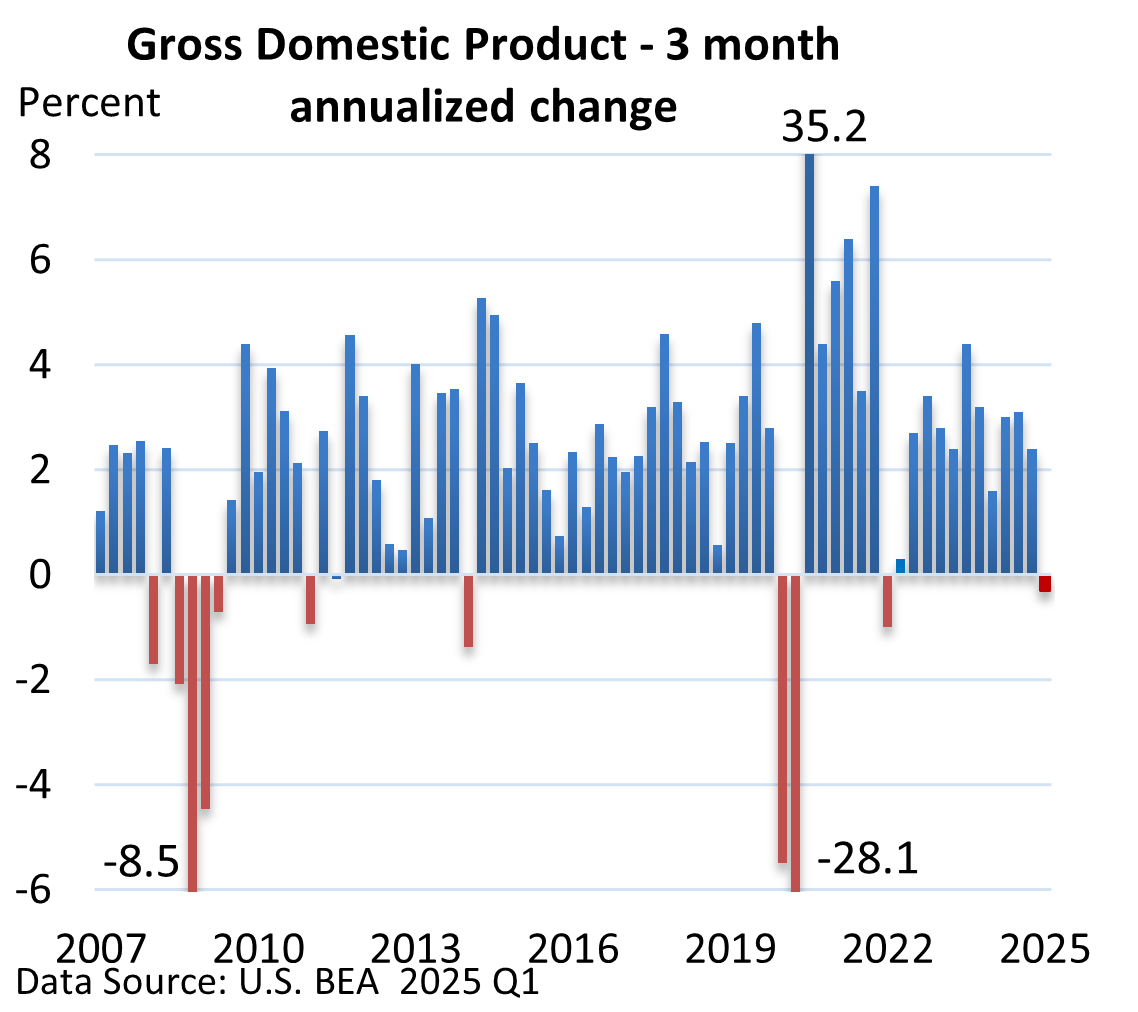
Yet, a closer look reveals that the economy didn’t shrink in Q1.

What happened? Businesses rushed to stockpile goods ahead of tariffs, which depressed GDP. Let’s explain with a simple example.

If Americans purchased 1,000 toasters in Q4 and companies imported 100 toasters from abroad, GDP, which measures domestic production, would effectively count 900 toasters, as 100 were imported.

If Americans purchased 1,100 toasters in Q1 and companies, anticipating tariffs, imported 300 toasters, this results in a net increase of 800 toasters, down from 900 in the previous period.

Although consumer purchases rose by 100, the spike in imports weighed on GDP.

In Q1, imports jumped a record 41% (quarterly GDP records began in 1947), which shaved a staggering five percentage points off GDP, according to the U.S. BEA.

However, companies did not sell the massive influx of imports, leaving some to accumulate in warehouses across the country.

This surge in inventories contributed more than two percentage points to GDP.

Why? Inventories act as a balancing figure—when they increase, it adds to GDP; when they decline, it detracts from GDP.

Net the two categories, and GDP would have expanded in the first quarter. We might expect some of this to unwind in the second and third quarters.

But given the distortions in trade data, the economy during the first three months of the year was healthier than the headline number suggested.

One final remark: even amid the high level of economic uncertainty, stocks have recently mounted an impressive rally, with the S&P 500 rising for nine straight days (MarketWatch data).

Despite higher tariffs that remain in place, investors are hopeful that the delay in the most stringent levies, coupled with the ‘hope’ of new trade agreements, will enable the economy to sidestep a recession.

author avatar
Mark Chandik

Reproduction Prohibited without Express Permission. Copyright FDP Wealth Management. All rights reserved. Advisory Services offered through FDP Wealth Management, LLC, a state Registered Investment Adviser and Valmark Advisers, Inc. a SEC Registered Investment Advisor. Securities offered through ValMark Securities, Inc., Member FINRA/SIPC. 130 Springside Drive, Suite 300, Akron, OH 44333-2431 800.765.5201 Prosperity Partners and FDP Wealth Management, LLC are separate entities from ValMark Securities, Inc. and Valmark Advisers, Inc. Prosperity Partners, FDP Wealth Management, LLC, ValMark Securities, Inc., Valmark Advisers Inc., and their representatives do not offer tax advice. You should consult your tax professional regarding your individual circumstances. Indices are unmanaged and cannot be invested directly in. Past performance is not a guarantee of future results.

Indices are unmanaged and do not incur fees, one cannot directly invest in an index. You should consult your tax professional regarding your individual circumstances. This information is provided by Financial Jumble, LLC. Financial Jumble, LLC is a separate entity from ValMark Securities, Inc. and ValMark Advisers, Inc.

RELATED POSTS

A Hotter August CPI Builds Rate Hike Momentum

First, let’s clarify that any attempt to predict the Federal Reserve’s actions this week is, at best, an educated guess. Fed Chair Kevin Warsh has struck a hawkish tone, and the odds of a quarter-point increase in the fed funds rate are 87%, according to the CME Group. It was 59% on September 4.

Behind the Jobs Report

On Friday, the US Bureau of Labor Statistics (BLS) reported that nonfarm payrolls rose by a much greater-than-expected 162,000 jobs in August. The unemployment rate held steady at 4.1%.

Location Location Location

The graphic below compares the change in home prices, adjusted for inflation, for various US cities. For example, the average USA home price has topped inflation by 238% since 1948. Why has there been such a wide trajectory in prices, and why have they proven so persistent?

Rising Yields Faily to Derail Stocks

This year, the stock market has risen significantly. Lingering worries about oil prices, inflation, the war with Iran, and the possibility of an AI bubble haven’t subsided. But the economy is expanding, corporate profits have been strong, and the S&P 500 Index set a new high last week, according to the Wall Street Journal.

All Gas, No Brakes: Profits Soar in Q2

In a solid earnings season, we’d generally expect S&P 500 companies to deliver double-digit profit growth, meaning earnings growth of at least 10% versus a year ago (20% tops). That’s not a hard-and-fast rule, but it provides a useful benchmark for evaluating the strength of a quarter.