author avatar
Mark Chandik

Dec 23, 2024

The Fed and the Punch Bowl

In a speech given nearly 70 years ago, then-Federal Reserve Chairman William McChesney Martin Jr. made a now-famous analogy when he said that during an expanding economy, the Fed should “remove the punch bowl” before the party gets out of hand.

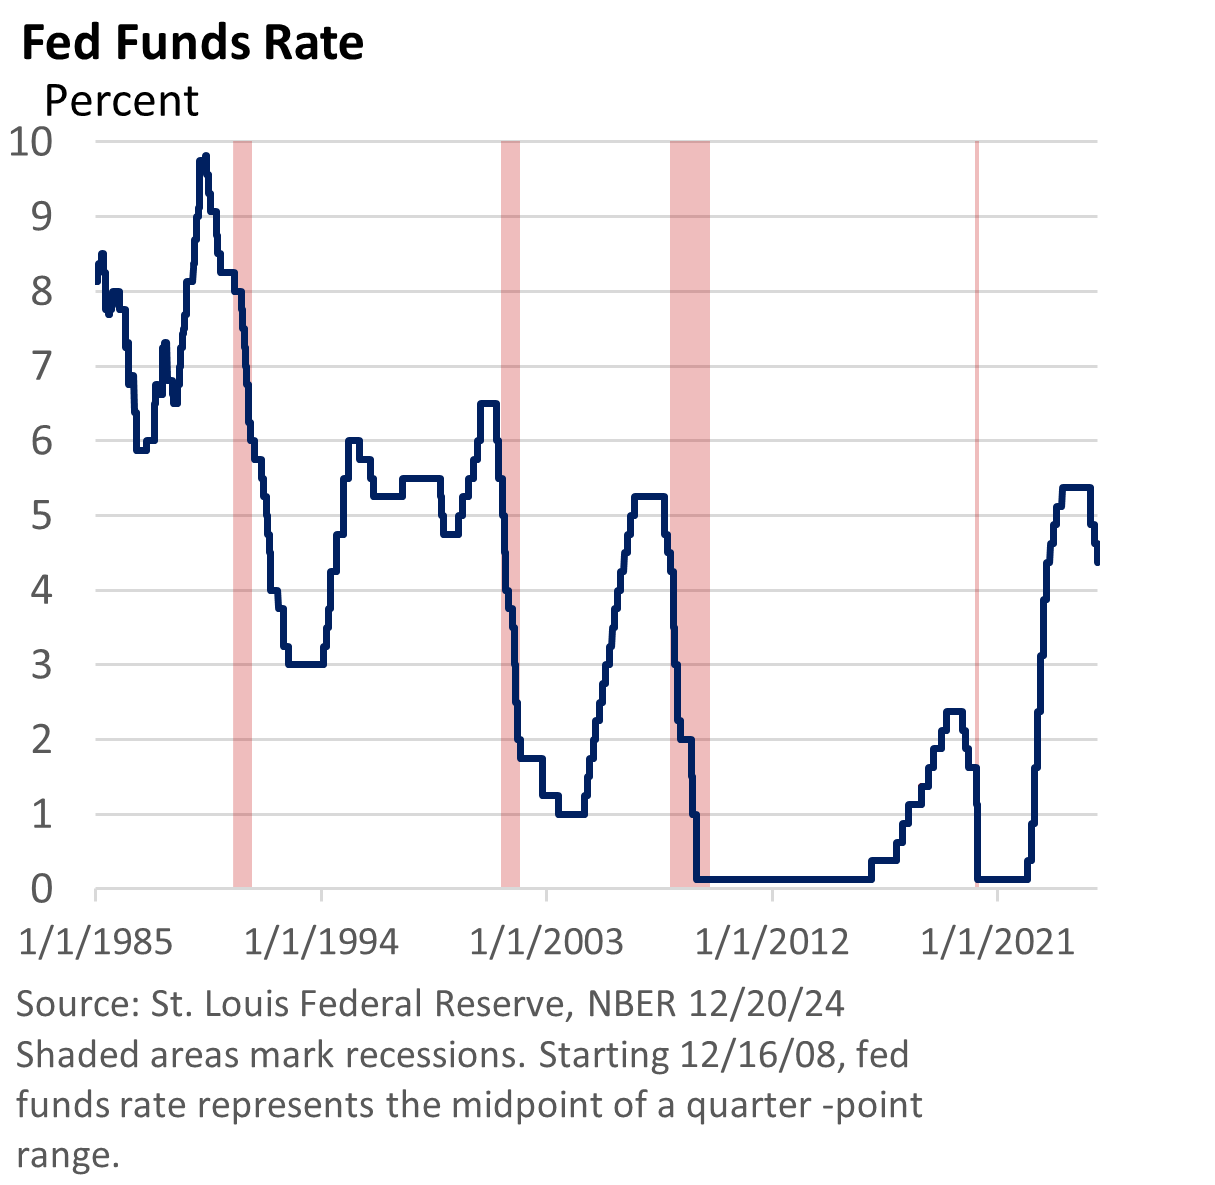
First things first, on Wednesday, the Fed reduced its key rate, the fed funds rate, by a quarter of a percentage point to 4.25 – 4.50%, as expected. It’s the third Fed rate cut in as many meetings.
So, why did the major indexes fall after the rate cut? The Wall Street Journal reported a drop in the Dow of over 1,100 points and a decline of nearly 3% for the S&P 500 Index.

While the Fed didn’t threaten to pull the punch bowl, the quarter-point rate cut was framed as a ‘hawkish’ rate cut.

The Fed didn’t threaten to raise rates, but Fed Chief Jay Powell signaled that the public shouldn’t expect rate cuts at consecutive meetings.

At his press conference, he said the Fed would be ‘cautious’ six times when discussing future rate cuts. The Fed is seeking “further progress on inflation” before additional reductions.

Released quarterly, the Fed now expects two rate cuts next year compared to four in September, according to its Economic Projections.

And the Fed raised its forecast for inflation next year.

And this is where things got confusing. If the economy is expanding at a respectable pace (Powell called it “remarkable”), and inflation has overshot expectations in recent months, why did the Fed move to cut rates again in December?

His explanation was nuanced and somewhat confusing, and stocks turned sharply lower on Wednesday.

As we’ve seen in the past, when equities are priced for perfection, a disappointment can lead to a pullback.

That leads us to the next question. Why the rebound on Friday? Well, the U.S. Bureau of Economic Analysis reported a soft inflation number for November.

Perspective

Stocks rarely move in a straight line. They go up, and they go down. But over the longer term, the major U.S. indexes have trended higher.

Second, stocks don’t need Fed rate cuts to move higher. More importantly, the economy is in decent shape, and corporate profits have been robust.

Third, the Fed hasn’t completely removed the punchbowl as it did in 2022.

author avatar
Mark Chandik

Reproduction Prohibited without Express Permission. Copyright FDP Wealth Management. All rights reserved. Advisory Services offered through FDP Wealth Management, LLC, a state Registered Investment Adviser and Valmark Advisers, Inc. a SEC Registered Investment Advisor. Securities offered through ValMark Securities, Inc., Member FINRA/SIPC. 130 Springside Drive, Suite 300, Akron, OH 44333-2431 800.765.5201 Prosperity Partners and FDP Wealth Management, LLC are separate entities from ValMark Securities, Inc. and Valmark Advisers, Inc. Prosperity Partners, FDP Wealth Management, LLC, ValMark Securities, Inc., Valmark Advisers Inc., and their representatives do not offer tax advice. You should consult your tax professional regarding your individual circumstances. Indices are unmanaged and cannot be invested directly in. Past performance is not a guarantee of future results.

Indices are unmanaged and do not incur fees, one cannot directly invest in an index. You should consult your tax professional regarding your individual circumstances. This information is provided by Financial Jumble, LLC. Financial Jumble, LLC is a separate entity from ValMark Securities, Inc. and ValMark Advisers, Inc.

RELATED POSTS

A Hotter August CPI Builds Rate Hike Momentum

First, let’s clarify that any attempt to predict the Federal Reserve’s actions this week is, at best, an educated guess. Fed Chair Kevin Warsh has struck a hawkish tone, and the odds of a quarter-point increase in the fed funds rate are 87%, according to the CME Group. It was 59% on September 4.

Behind the Jobs Report

On Friday, the US Bureau of Labor Statistics (BLS) reported that nonfarm payrolls rose by a much greater-than-expected 162,000 jobs in August. The unemployment rate held steady at 4.1%.

Location Location Location

The graphic below compares the change in home prices, adjusted for inflation, for various US cities. For example, the average USA home price has topped inflation by 238% since 1948. Why has there been such a wide trajectory in prices, and why have they proven so persistent?

Rising Yields Faily to Derail Stocks

This year, the stock market has risen significantly. Lingering worries about oil prices, inflation, the war with Iran, and the possibility of an AI bubble haven’t subsided. But the economy is expanding, corporate profits have been strong, and the S&P 500 Index set a new high last week, according to the Wall Street Journal.

All Gas, No Brakes: Profits Soar in Q2

In a solid earnings season, we’d generally expect S&P 500 companies to deliver double-digit profit growth, meaning earnings growth of at least 10% versus a year ago (20% tops). That’s not a hard-and-fast rule, but it provides a useful benchmark for evaluating the strength of a quarter.